Introduction
Compulsory car insurance, known in many countries as third-party liability insurance, is the minimum legal requirement for vehicle owners. It’s designed to cover the cost of injury or death to others in the event of an accident caused by the insured driver. While this baseline coverage is crucial for protecting public welfare and promoting road safety, many drivers assume it offers more protection than it actually does.
In reality, relying solely on compulsory car insurance can leave you dangerously exposed—both financially and legally. It’s a safety net, not a comprehensive solution. For drivers who want to truly protect themselves, their passengers, and their vehicles, understanding the limitations of compulsory insurance is essential.
This article breaks down the hidden risks of depending only on mandatory coverage and explains why additional protection is worth the investment.
What Is Compulsory Car Insurance?
Definition and Purpose
Compulsory car insurance, sometimes referred to as CTPL (Compulsory Third Party Liability) in countries like the Philippines or ประกันภัยภาคบังคับ (พ.ร.บ.) in Thailand, is required by law before a vehicle can be registered or operated.
What It Covers:
- Medical costs for injured third parties (e.g., pedestrians, other drivers)
- Funeral expenses if a third party dies as a result of the accident
- In some cases, basic compensation to passengers in your vehicle
What It Does Not Cover:
- Damage to your own vehicle
- Injuries to yourself as the driver
- Theft, fire, or vandalism
- Damage to property, such as buildings, fences, or other cars
- Loss of income or legal fees
For many drivers, these gaps only become apparent after an accident happens—often too late to avoid major financial consequences.
1. You’re Still Financially Responsible for Your Own Damages
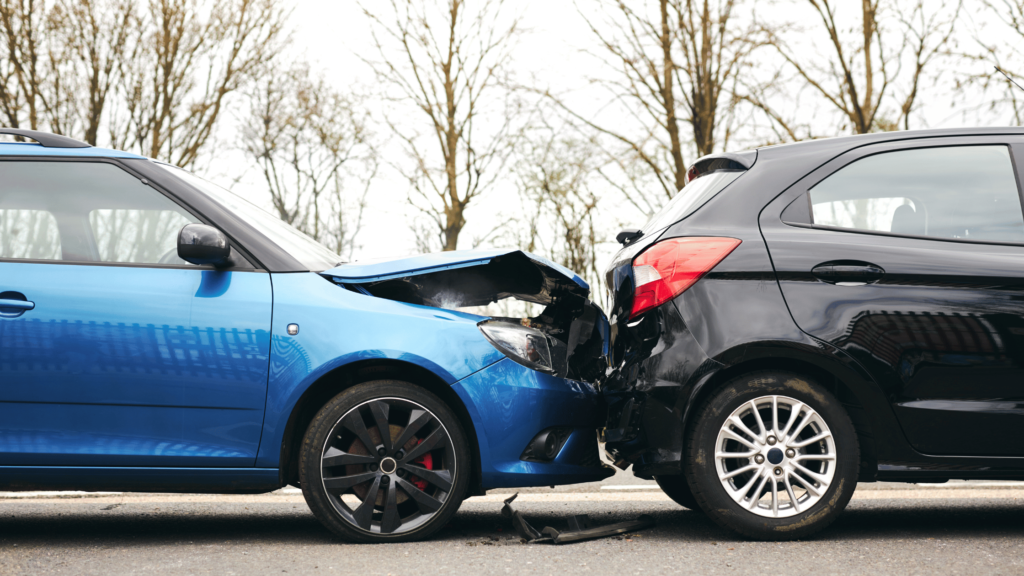
While compulsory insurance helps pay for injuries to others, it offers no support for your own losses. If your car is damaged in an accident—whether you’re at fault or not—you’ll have to cover the repair or replacement costs out of pocket.
Example:
If you crash into a tree or get hit by an uninsured driver, compulsory insurance won’t pay a cent for the repairs. Even a minor fender bender can cost tens of thousands in parts and labor.
This makes relying solely on compulsory insurance a risky gamble, especially in areas with high accident rates or costly repairs.
2. No Protection Against Theft or Natural Disasters
Car theft, floods, hail, falling trees, and fire are all real risks, particularly in urban environments or flood-prone areas. Unfortunately, none of these are covered under compulsory car insurance.
Real-World Scenario:
Imagine parking your car on the street during a heavy storm, only to find it totaled by a fallen billboard. Without voluntary (comprehensive) insurance, you’re facing a total loss—one that compulsory coverage won’t touch.
Comprehensive policies, on the other hand, typically cover a wide range of non-collision-related events, offering peace of mind in unpredictable circumstances.
3. Legal Liability Can Go Beyond Medical Costs
One of the most misunderstood aspects of compulsory insurance is that it limits how much it will pay for third-party injuries or deaths. In serious cases involving long-term care or lawsuits, the payouts from compulsory coverage may not be enough.
If you’re found legally liable for additional damages, you could be sued for the remaining balance—putting your personal assets at risk.
Key Risk:
- Court awards can exceed compulsory coverage limits
- You may be responsible for legal fees and settlement costs
- Your license could be suspended or your assets seized if you can’t pay
Optional insurance policies (such as third-party property damage or personal accident coverage) are designed to fill this legal and financial gap.
4. Injuries to the Driver Are Not Covered
In the event of an accident, compulsory insurance often excludes the driver’s own medical expenses. While your passengers may be partially covered, you—the person most at risk—could be left to handle the medical bills yourself.
Medical Costs May Include:
- Emergency room visits
- Surgery or hospitalization
- Physical therapy and rehabilitation
- Income lost due to time off work
By contrast, voluntary personal accident coverage can provide funds for driver injuries, disability, and even death benefits.
5. No Roadside Assistance or Added Benefits
Modern auto insurance isn’t just about accident payouts—it also includes a range of value-added services that compulsory insurance lacks:
- 24/7 roadside assistance
- Free towing services
- Car replacement while yours is in the shop
- Legal consultation
- Coverage in cross-border travel (e.g., into neighboring countries)
If you’ve ever had a flat tire, battery failure, or breakdown in the middle of nowhere, you’ll understand the real-world value of these support features.
6. Limited Claim Process and Compensation Speed
Compulsory insurance claims are often slow and bureaucratic, especially in public systems or highly regulated markets. With capped payouts and limited flexibility, you may not be compensated quickly—or fairly.
Voluntary insurance, particularly through private providers, often delivers faster claims handling, better customer support, and more customizable policy options tailored to your lifestyle and risk level.
7. The False Sense of Security
Perhaps the biggest risk of all is the illusion of being fully protected. Many drivers assume that having compulsory insurance means they’re “covered”—and only realize the truth when they’re hit with repair bills, legal demands, or medical expenses.
In reality, compulsory coverage is designed to protect others from your negligence, not to protect you. A well-rounded policy is the only way to ensure both personal and financial security on the road.
Conclusion
Compulsory car insurance is important—it’s the legal minimum that promotes road safety and ensures that victims of accidents receive at least basic compensation. But make no mistake: it’s not designed to fully protect you or your vehicle.
By relying solely on compulsory coverage, you leave yourself open to:
- Out-of-pocket repair costs
- Medical bills for your own injuries
- Liability lawsuits
- Total losses from theft, fire, or floods
- Delays and limitations in claims processing
Smart drivers take a proactive approach by investing in additional coverage—whether it’s third-party property damage, personal accident insurance, or full comprehensive plans. These policies don’t just offer peace of mind; they help you stay financially resilient in the face of the unexpected.
In a world where the road ahead is always uncertain, don’t settle for the legal minimum. Protect what matters most—your car, your health, and your financial future.